







Travel merchant account: risk, regulation and payment data
Alon Shkuri · 20 Oct 2026 · 6 MIN READ
Getting a travel merchant account is harder than setting up card acceptance for almost any other business, and the reason is timing. A traveller pays months before the trip happens, so the company that processes the card payment carries risk for the whole period in between. For tour operators and travel sellers, the way they handle payments and the data around them decides what that account costs, how much paperwork it brings and how much cash stays tied up.
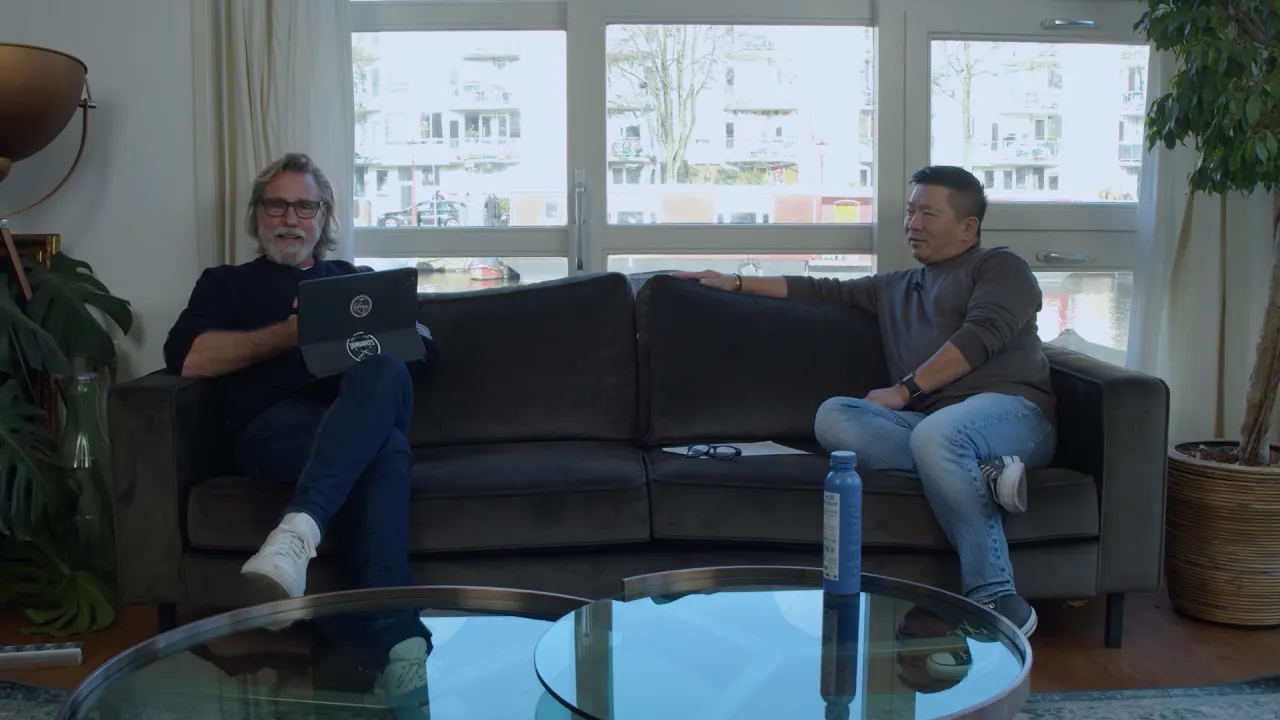
Will Bicknell knows both sides of the problem. He set up a tour operator in the UK with three friends from university, and payments were the thing that kept them up at night. Later he worked as chief innovation officer at a fintech company, where he designed a new type of credit card and learned how banking systems and underwriting work. He then founded Felloh, a payments platform for travel that sees itself as a data company first. His view: payments are not just a cost centre, they are a source of data that can help a travel business run and grow.
Why a travel merchant account carries extra risk
A merchant acquirer is the company that lets you process credit and debit cards on the Visa, Mastercard and American Express schemes. You have taken the customer's money but not yet delivered the holiday, and if the travel company fails in between, or one of its suppliers does, the customer still needs their money back.
“Somebody's got to refund that customer. And that causes a risk and exposure for those merchant acquirers.”
Will Bicknell, 4:59
That exposure is why an acquirer wants to understand what is going on inside a travel business before it decides which services to offer and what to charge for them. At the same time, package travel rules (the package travel regulations in the UK, the package travel directive across Europe) exist to reassure the consumer: if the holiday does not go ahead, they get their money back. In Bicknell's experience those two sides do not talk to each other very well, and the travel company ends up in the middle, trying to satisfy the regulation while keeping its acquirer comfortable.
The data that acquirers and regulators want to see
Bicknell's answer to that squeeze is data. If you can share accurately and simply what is happening in your business, it becomes easier to comply with the regulation and easier to work with payment companies. He names the information that matters:
- When each customer paid.
- When they are travelling.
- How they paid: credit card, debit card or bank transfer.
- How that money is protected, for example in a trust account, with a bond or through an insurance policy.
Keeping this accurate and easy to share with partners is, in his view, what helps a travel company going forward. He points to open banking in the UK as an example: a credit card payment has consumer protection built in, while an open banking payment does not. That may mean someone else has to protect the funds the customer paid, and regulators still have to work out how to deal with that. A related article looks at alternative payment methods in travel.
“Higher quality, trustworthy data that you can share with other people is definitely a competitive advantage.”
Will Bicknell, 14:43
Stop taking card payments over the phone
The habit that surprises Bicknell most is how often travel companies still take payments on the phone. It tells customers they have to be available when the company wants them, it exposes the business to staff writing card numbers down or typing them into a screen outside a secure area, and it skips 3D Secure, the secondary check where the customer confirms it really is them making the payment. Without that authentication, he says, the company is exposed to a chargeback or a fraud claim on those payments.
Payment links are not new, but many travel companies he meets still do not use them. A link lets the customer pay in their own time, removes the phone call and lowers the fraud risk. The same logic applies to the rest of the payment schedule: instalments can be collected automatically, and even a simple deposit and final balance can run without anyone chasing the customer.
Payment metrics to watch on your travel merchant account
Bicknell suggests a few numbers that apply to almost every travel business, from small niche operators to volume players:
- The success rate of payments going through.
- How much manual time the team spends managing payments.
- How many customer questions come in about payments. There should not be many.
- The cost of each transaction, especially for international customers. Cards from the United States, for example, carry higher fees, and some of those can be surcharged to recover the cost.
His broader advice is simple: have someone look at all the data your travel merchant account produces. A dashboard is enough to see where time or money is leaking. A related article looks at pricing from another angle: vacation rental pricing strategy.
Automating reconciliation and supplier invoices
The finance team faces a different problem. The acquirer pays out one large lump of money, and someone has to work out which payments, refunds and charges are inside it before it can be reconciled. The first step he suggests for most operators is to connect payment data to bank information so reconciliation happens on its own.
“Connecting your payments data with your bank information and then reconciling that automatically. That would be a very simple baby step for people to take that would have a lot of value to them.”
Will Bicknell, 19:51
He sees the back office as the place where AI is useful today. Travel companies receive many supplier invoices, and a team reads each one to find out who it is from, what it is for and which booking it belongs to. Language models and related tools can read those invoices, pick out the supplier name, booking reference or customer name and match them up. A human still needs to stay in the loop, because the tools will not get it right every time. Done at scale, it saves a lot of time and lets the company pay suppliers at the moment that suits its cashflow best.
A first step for a small operator
None of this requires a tech team. Bicknell describes a specialist operator running group tours for about a hundred people, each with a different price because travellers added their own extras. Everything lived in spreadsheets, and collecting payments meant creating links by hand or phoning customers. Using Zapier, a new row in the spreadsheet now triggers a payment link with exactly the right amount and the right reference. As soon as the customer pays, the spreadsheet updates itself. A related article looks at what it takes to start a travel company.
Bicknell's ideal is a payment that feels invisible: the customer gets an alert, pays and authenticates on their phone, and the back office tells the right people and updates the right system. You can watch the full conversation or explore more episodes in the Travel Commerce Unfiltered series.
Frequently asked questions
Why is a travel merchant account harder to get than a normal one?
Customers pay long before they travel. If the travel company or one of its suppliers fails in between, someone has to refund the customer, and that exposure sits with the merchant acquirer. Acquirers therefore want to understand how a travel business works before deciding which services to offer and what to charge, so clear data about bookings and protection helps.
What payment data should a tour operator keep?
Keep a record of when each customer paid, when they travel, how they paid (credit card, debit card or bank transfer) and how the money is protected, for example in a trust account, with a bond or through insurance. Accurate, shareable data makes it easier to satisfy regulators and payment partners, and in Will Bicknell's view it can lower costs.
Is it safe to take card payments over the phone?
It is risky. Staff may write card numbers down or type them in outside a secure area, and phone payments skip 3D Secure, the extra check that confirms the cardholder is paying. That leaves the business exposed to chargebacks and fraud claims. Payment links let customers pay securely in their own time instead.